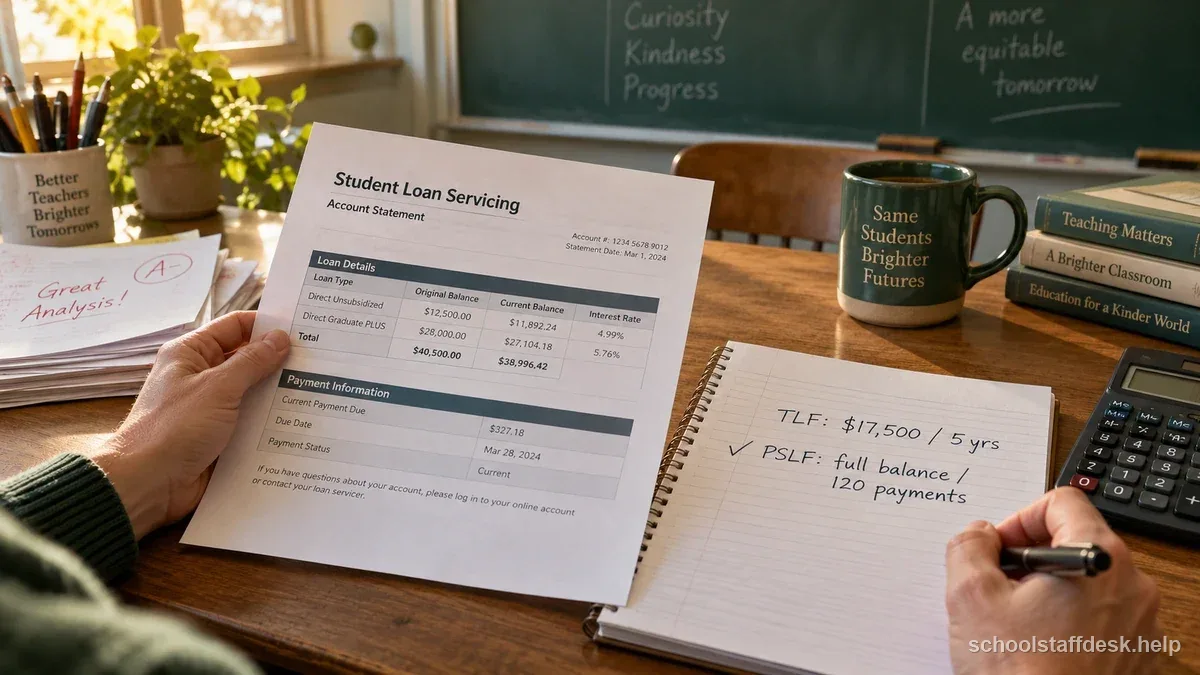
What Teacher Loan Forgiveness actually requires
TLF is for full-time classroom teachers—not counselors, librarians, aides, or other school staff—who complete five consecutive, complete academic years at a qualifying low-income school or educational service agency. It can forgive up to $5,000 on eligible Direct Subsidized/Unsubsidized or Federal Stafford Subsidized/Unsubsidized loans; up to $17,500 is available to highly qualified secondary math/science teachers and qualifying special education teachers at any level. PLUS and Perkins loans are not eligible, and a consolidation loan qualifies only to the extent it repaid eligible loan types.
The federal definition of "highly qualified" depends on the teacher's level, school type, and applicable state testing or certification route; do not reduce it to a blanket requirement for full state certification in every case. A qualifying partial year is excused only in limited circumstances—generally at least half the academic year, related postsecondary study at least half time, a qualifying FMLA reason, or active military duty exceeding 30 days, plus employer certification that contract requirements were fulfilled. Check the current application and eligible-school directory for each year.
What PSLF actually requires, and how it differs
PSLF can forgive the remaining balance on eligible Direct Loans after 120 qualifying monthly payments while you work full time for a qualifying public-service employer. The payments need not be consecutive. A government school district generally qualifies; a private school's status depends on the employer's tax and program eligibility, not simply the fact that it is a school. PSLF does not require a teaching subject or low-income school, but each month must meet the loan, employer, work-hours, and repayment-plan rules in force for your loan cohort.
FFEL and Perkins loans are not PSLF-eligible unless handled under a qualifying consolidation/loan rule; consolidation can affect payment counts, interest, and other benefits. Parent PLUS has additional consolidation and repayment restrictions. New repayment rules took effect for certain loans in 2026, so use StudentAid.gov's current PSLF and repayment-plan guidance for each loan before consolidating, changing plans, or assuming a 120-payment schedule.
- First qualifying yearsThe five-year service period used for TLF cannot also count toward PSLF; distinct qualifying months must be tracked separately.
- TLF applicationTLF follows five consecutive qualifying teaching years.
- PSLF pathPSLF requires 120 qualifying monthly payments; prior unrelated qualifying months are not automatically erased.
- Before choosingCompare your loan balance and plans using your own program records.
The sequencing problem: you cannot double-count the same payments
You cannot receive TLF and PSLF benefits for the same period of teaching service. Federal Student Aid says that if you make payments during five qualifying TLF years and then receive TLF for that service, those payments do not count toward PSLF. Its current TLF guidance also says service already counted toward PSLF/TEPSLF does not count toward TLF's five-year requirement. Treat the service dates and loan balances together; do not assume that filing one application leaves the same five years available for the other program.
The programs can still be used sequentially for distinct service periods and eligible loans—for example, TLF after five qualifying years and PSLF later after a separate period that satisfies its payment and employment rules. Whether this produces more value depends on your current balance, expected payments, forgiveness amount, tax and interest effects, and how long you expect to remain with a qualifying employer. Use StudentAid.gov Loan Simulator and your official payment record instead of assuming that PSLF or TLF always pays more.
TLF vs. PSLF at a glance
| Teacher Loan Forgiveness | PSLF | |
|---|---|---|
| Forgiveness amount | Up to $17,500 (or $5,000 depending on subject) | Entire remaining balance |
| Time required | 5 consecutive years teaching | 120 payments (10 years, not necessarily consecutive) |
| Work requirement | Full-time teacher at a qualifying low-income school/ESA | Full-time work for a qualifying public-service employer; teaching is not required |
| Subject requirement | $17,500 tier limited to math/science/special ed | None |
| Eligible loans | Eligible Direct and FFEL Stafford loans; PLUS/Perkins excluded | Eligible Direct Loans; some other federal loans may qualify only under current consolidation rules |
| Can the same service count twice? | No; time used for TLF cannot also satisfy PSLF | No; keep qualifying PSLF months from distinct service periods separately documented |
When TLF is still the better choice
TLF may be worth comparing when the eligible balance is near or below its $5,000/$17,500 cap, you may not complete 120 PSLF payments, or your teaching/employer plans do not meet PSLF rules. Before applying, check whether the service period has already been counted toward PSLF/TEPSLF; the programs do not permit a double benefit for the same service. PSLF employment forms are recommended regularly to keep an accurate record, though a form is not required every single year. TLF is applied for after the required teaching years, using the current form certified by the school's authorized official.
A worked example
Consider a special education teacher with $60,000 in eligible Direct Loans. TLF might forgive up to $17,500 after five qualifying teaching years; PSLF might forgive a remaining balance after 120 qualifying payments, but only if the teacher's employer, work hours, loan, and repayment plan qualify. The same five years cannot support both benefits. The amounts actually paid under each path depend on balance, income, family size, interest, and future employment, so the loan balance alone does not identify the better choice.
Run at least two scenarios in Federal Student Aid's Loan Simulator, then confirm loan-by-loan eligibility and your recorded PSLF months. Include Parent PLUS/FFEL loans separately, avoid counting one service period twice, and compare likely forgiveness after projected payments rather than comparing only the $17,500 cap with the starting balance.
Where to actually check your progress
For PSLF, use the Help Tool and employment form to check employer eligibility and update your qualifying payment count; Federal Student Aid recommends periodic certification so problems surface earlier, though it is not required every year. For TLF, apply after completing the qualifying service with the current Teacher Loan Forgiveness Application signed by an authorized school or educational-service-agency official. Keep the service dates and affected loan accounts with both records so you do not claim the same period for both benefits.
What to do right now if you're not sure which path you're on
List each loan type, current balance, original disbursement date, repayment plan, and whether it includes Parent PLUS debt. Check your official PSLF payment count and the dates already credited; verify each school/ESA year in the TCLI directory and whether the work meets TLF's teacher and subject criteria. Then model distinct service periods in Loan Simulator and confirm any loan-specific question with Federal Student Aid or your servicer before consolidating or applying.
Sources used for this guide
- Federal Student Aid — 4 Loan Forgiveness Programs for Teachers
- Federal Student Aid — Teacher Loan Forgiveness Application
- NEA — Frequently Asked Questions on Student Loan Forgiveness
- Federal Student Aid — Public Service Loan Forgiveness
Rules can change. Use these sources as a starting point and confirm any state, district, student-plan, employment, licensing, or retirement requirement with the agency or team that governs your situation.
Questions school staff ask about this situation
Can I do TLF and then start PSLF afterward?
Potentially, if the later service and payments independently meet PSLF rules. The five-year service period used for TLF cannot also count toward PSLF, but that does not automatically erase PSLF months from a different period; confirm the dates and affected loans in your official record.
Do I need to pick one program and stick with it from day one?
Not necessarily. Compare loan-by-loan balances, credited PSLF months, TLF school and subject eligibility, expected payments, and the service dates each program would use. A long career by itself does not establish which path produces the better result.
Does National Board Certification or advanced degrees affect either program?
Neither program's forgiveness amount changes based on National Board Certification or advanced degrees. Both are separate from state-level salary schedule benefits those credentials may unlock.
What happens to my PSLF progress if I leave teaching for a private-sector job for a few years?
Payments generally qualify only for months that meet the applicable loan, payment, and qualifying-employment rules. Months that do not qualify do not count toward 120, but previously qualifying months are not erased merely because you later leave qualifying employment. Check current rules for your loan and repayment cohort.